 otbenchmark
Note
Go to the end to download the full example code.
Convergence of estimators on Ishigami
In this example, we present the convergence of the sensitivity indices of the Ishigami test function.
We compare different estimators.
Sampling methods with different estimators: Saltelli, Mauntz-Kucherenko, Martinez, Jansen,
Sampling methods with different design of experiments: Monte-Carlo, LHS, Quasi-Monte-Carlo,
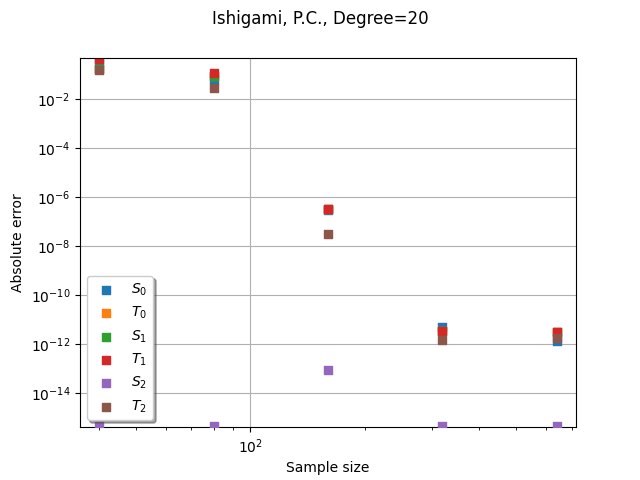
Polynomial chaos.
import openturns as ot
import otbenchmark as otb
import openturns.viewer as otv
import numpy as np
maximumElapsedTime = 0.5
When we estimate Sobol’ indices, we may encounter the following warning messages:
`
WRN - The estimated first order Sobol index (2) is greater than its total order index...
WRN - The estimated total order Sobol index (2) is lesser than first order index ...
`
Lots of these messages are printed in the current Notebook. This is why we disable them with:
ot.Log.Show(ot.Log.NONE)
problem = otb.IshigamiSensitivity()
print(problem)
name = Ishigami
distribution = JointDistribution(Uniform(a = -3.14159, b = 3.14159), Uniform(a = -3.14159, b = 3.14159), Uniform(a = -3.14159, b = 3.14159), IndependentCopula(dimension = 3))
function = ParametricEvaluation([X1,X2,X3,a,b]->[sin(X1) + a * sin(X2)^2 + b * X3^4 * sin(X1)], parameters positions=[3,4], parameters=[a : 7, b : 0.1], input positions=[0,1,2])
firstOrderIndices = [0.313905,0.442411,0]
totalOrderIndices = [0.557589,0.442411,0.243684]
distribution = problem.getInputDistribution()
model = problem.getFunction()
Exact first and total order
exactFirstOrder = problem.getFirstOrderIndices()
print(exactFirstOrder)
exactTotalOrder = problem.getTotalOrderIndices()
print(exactTotalOrder)
[0.313905,0.442411,0]
[0.557589,0.442411,0.243684]
Perform sensitivity analysis
Create X/Y data
ot.RandomGenerator.SetSeed(0)
size = 10000
inputDesign = ot.SobolIndicesExperiment(distribution, size).generate()
outputDesign = model(inputDesign)
Compute first order indices using the Saltelli estimator
sensitivityAnalysis = ot.SaltelliSensitivityAlgorithm(inputDesign, outputDesign, size)
computedFirstOrder = sensitivityAnalysis.getFirstOrderIndices()
computedTotalOrder = sensitivityAnalysis.getTotalOrderIndices()
Compare with exact results
print("Sample size : ", size)
# First order
# Compute absolute error (the LRE cannot be computed,
# because S can be zero)
print("Computed first order = ", computedFirstOrder)
print("Exact first order    = ", exactFirstOrder)
# Total order
print("Computed total order = ", computedTotalOrder)
print("Exact total order    = ", exactTotalOrder)
Sample size :  10000
Computed first order =  [0.302745,0.460846,0.0066916]
Exact first order    =  [0.313905,0.442411,0]
Computed total order =  [0.574996,0.427126,0.256689]
Exact total order    =  [0.557589,0.442411,0.243684]
dimension = distribution.getDimension()
Compute componentwise absolute error.
firstOrderAE = ot.Point(np.abs(exactFirstOrder - computedFirstOrder))
totalOrderAE = ot.Point(np.abs(exactTotalOrder - computedTotalOrder))
print("Absolute error")
for i in range(dimension):
    print(
        f"AE(S{i}) = {firstOrderAE[i]:.4f}, AE(T{i}) = {totalOrderAE[i]:.4f}"
    )
Absolute error
AE(S0) = 0.0112, AE(T0) = 0.0174
AE(S1) = 0.0184, AE(T1) = 0.0153
AE(S2) = 0.0067, AE(T2) = 0.0130
metaSAAlgorithm = otb.SensitivityBenchmarkMetaAlgorithm(problem)
for estimator in ["Saltelli", "Martinez", "Jansen", "MauntzKucherenko", "Janon"]:
    print("Estimator:", estimator)
    benchmark = otb.SensitivityConvergence(
        problem,
        metaSAAlgorithm,
        numberOfRepetitions=4,
        maximumElapsedTime=maximumElapsedTime,
        sampleSizeInitial=20,
        estimator=estimator,
    )
    grid = benchmark.plotConvergenceGrid(verbose=False)
    view = otv.View(grid)
    figure = view.getFigure()
    _ = figure.suptitle(f"{problem.getName()}, {estimator}")
    figure.set_figwidth(10.0)
    figure.set_figheight(5.0)
    figure.subplots_adjust(wspace=0.4, hspace=0.4)
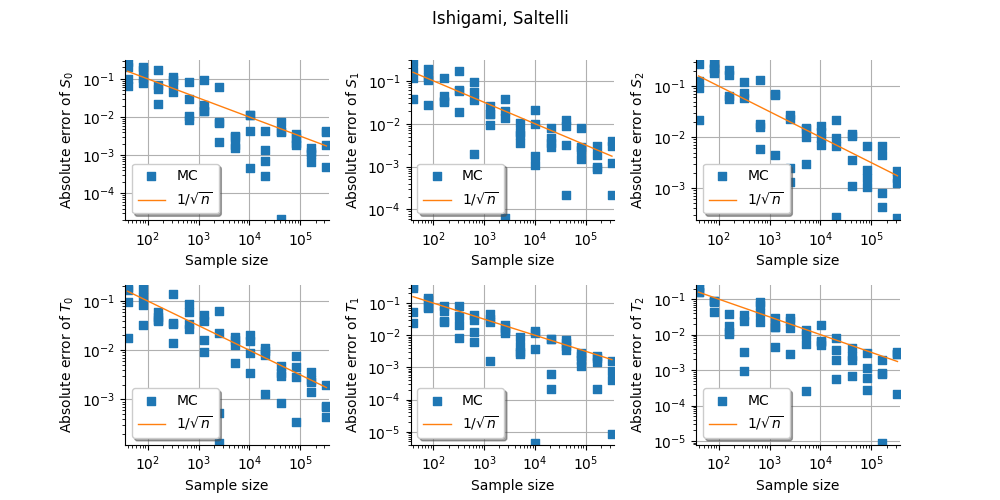
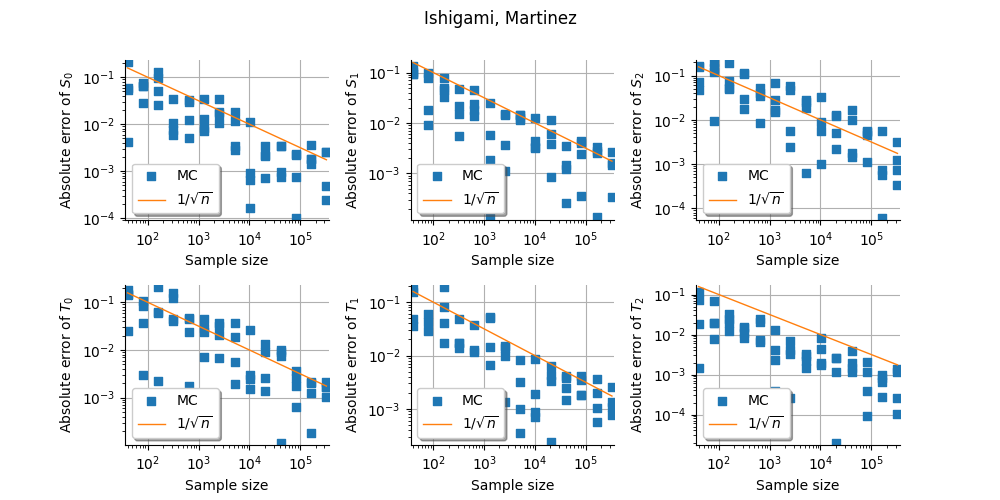
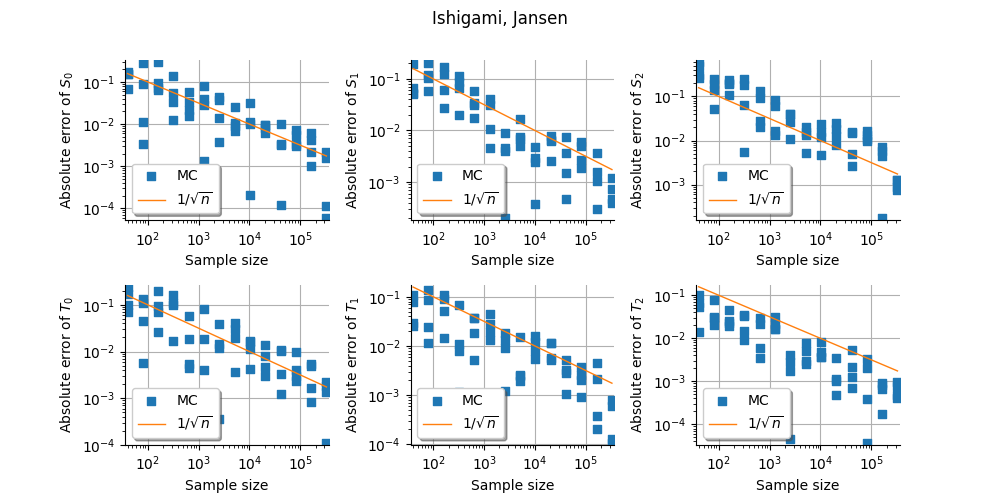
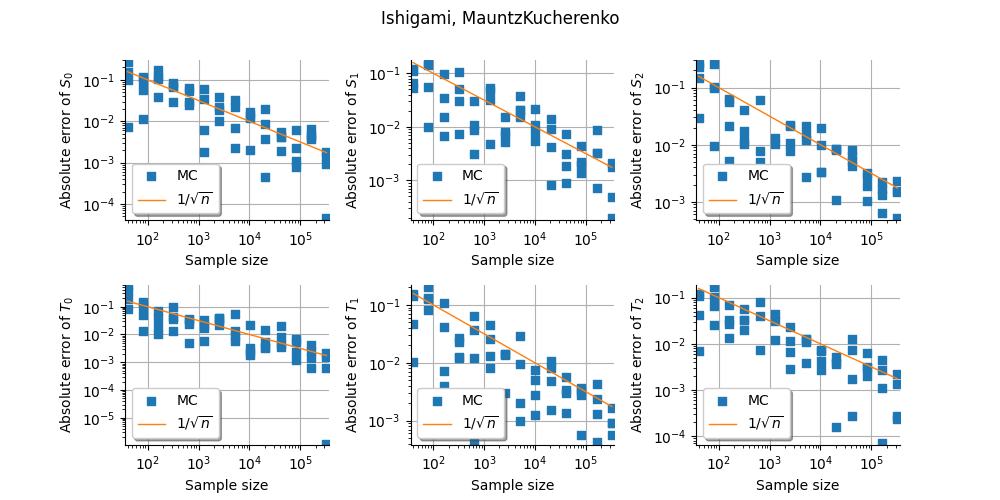
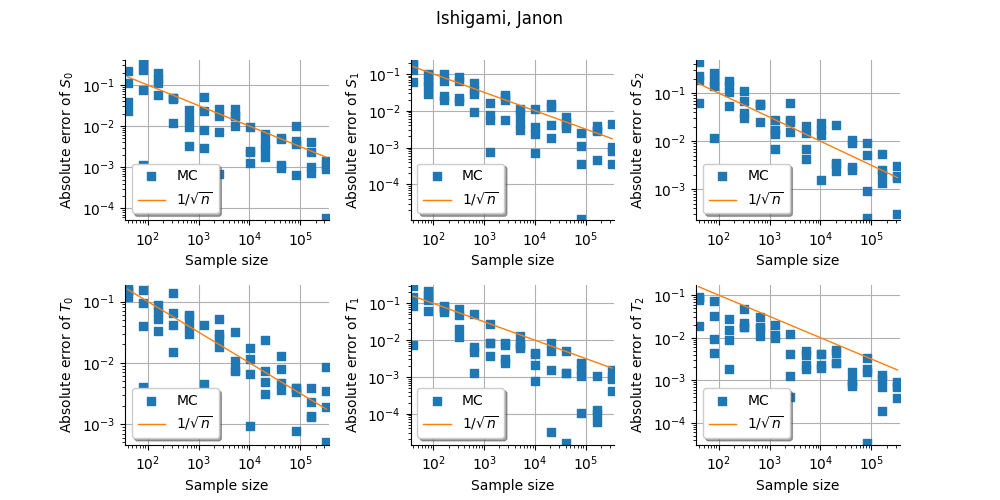
Estimator: Saltelli
Estimator: Martinez
Estimator: Jansen
Estimator: MauntzKucherenko
Estimator: Janon
benchmark = otb.SensitivityConvergence(
    problem,
    metaSAAlgorithm,
    numberOfRepetitions=4,
    maximumElapsedTime=maximumElapsedTime,
    sampleSizeInitial=20,
    estimator="Saltelli",
    samplingMethod="MonteCarlo",
)
graph = benchmark.plotConvergenceCurve()
graph.setLegendPosition("upper left")
graph.setLegendCorner((1.0, 1.0))
_ = otv.View(graph, figure_kw={"figsize": (4.0, 3.0)})
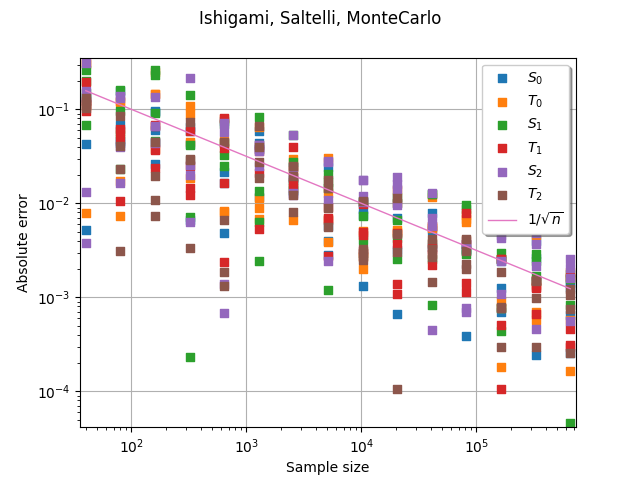
grid = ot.GridLayout(1, 3)
maximumAbsoluteError = 1.0
minimumAbsoluteError = 1.0e-5
samplingMethodList = ["MonteCarlo", "LHS", "QMC"]
estimator = "Saltelli"
for samplingMethodIndex, samplingMethod in enumerate(samplingMethodList):
    samplingMethod = samplingMethodList[samplingMethodIndex]
    benchmark = otb.SensitivityConvergence(
        problem,
        metaSAAlgorithm,
        numberOfRepetitions=4,
        maximumElapsedTime=maximumElapsedTime,
        sampleSizeInitial=20,
        estimator=estimator,
        samplingMethod=samplingMethod,
    )
    graph = benchmark.plotConvergenceCurve()
    # Change bounding box
    box = graph.getBoundingBox()
    bound = box.getLowerBound()
    bound[1] = minimumAbsoluteError
    box.setLowerBound(bound)
    bound = box.getUpperBound()
    bound[1] = maximumAbsoluteError
    box.setUpperBound(bound)
    graph.setBoundingBox(box)
    if samplingMethodIndex < len(samplingMethodList) - 1:
        graph.setLegends([""])
    else:
        graph.setLegendPosition("upper left")
        graph.setLegendCorner((1.0, 1.0))
    if samplingMethodIndex > 0:
        graph.setYTitle("")
    graph.setTitle(f"{samplingMethod}")
    grid.setGraph(0, samplingMethodIndex, graph)
grid.setTitle(f"Ishigami, {estimator}")
_ = otv.View(grid, figure_kw={"figsize": (8.0, 4.0)})
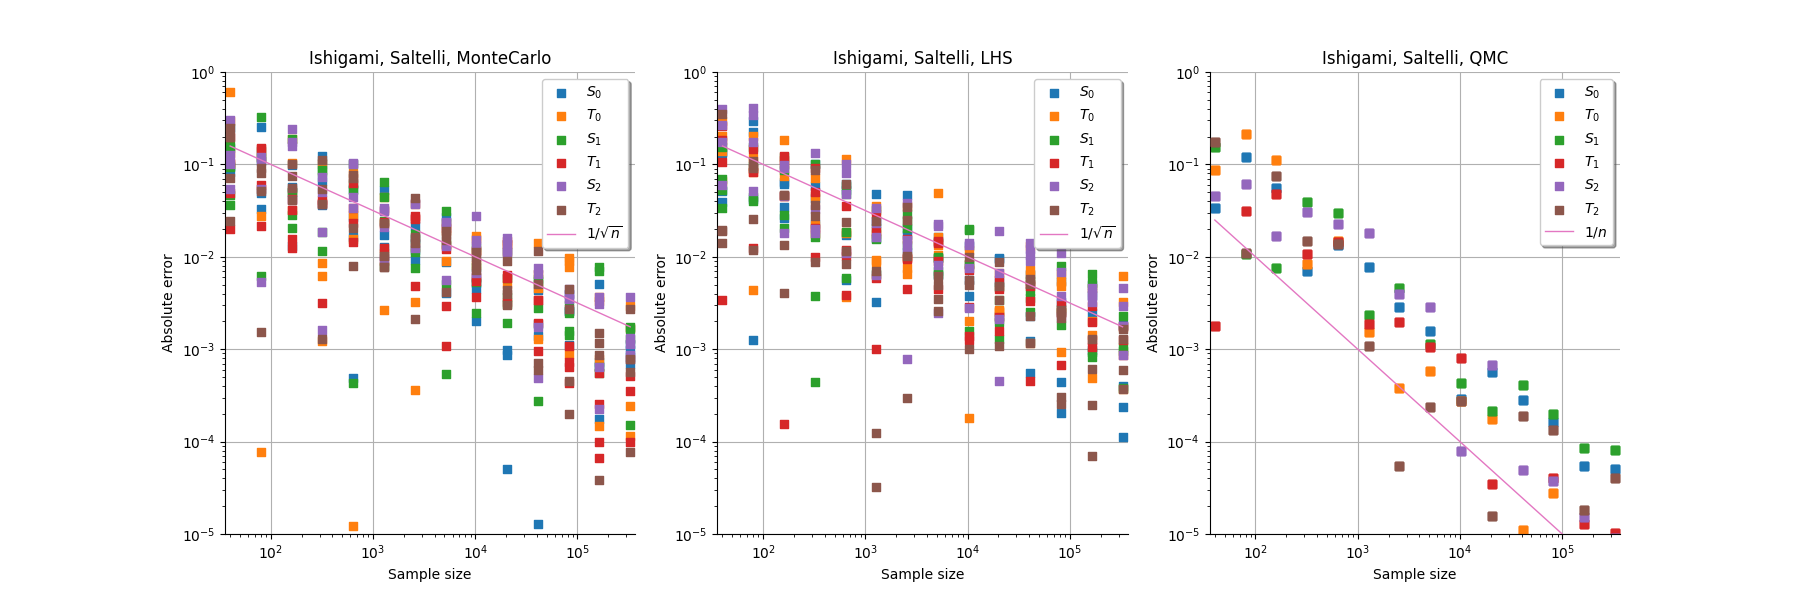
Use polynomial chaos.
sparse = True
benchmark = otb.SensitivityConvergence(
    problem,
    metaSAAlgorithm,
    numberOfExperiments=12,
    numberOfRepetitions=1,
    maximumElapsedTime=5.0,
    sampleSizeInitial=80,
    useSampling=False,
    totalDegree=8,
    hyperbolicQuasiNorm=1.0,
    sampleSizeFactor=1.5,
    sparse=sparse,
)
graph = benchmark.plotConvergenceCurve(verbose=True)
graph.setLegendPosition("upper left")
graph.setLogScale(ot.GraphImplementation.LOGX)
graph.setLegendCorner((1.0, 1.0))
_ = otv.View(graph, figure_kw={"figsize": (4.0, 3.0)})
Elapsed = 0.0 (s), Sample size = 80
Error in experiment 0, repetition 0, sample size 80: The number of candidate coefficients is 165 is larger or equal to the sample size 80
Elapsed = 0.0 (s), Sample size = 120
Error in experiment 1, repetition 0, sample size 120: The number of candidate coefficients is 165 is larger or equal to the sample size 120
Elapsed = 0.0 (s), Sample size = 180
Elapsed = 0.0 (s), Sample size = 270
Elapsed = 0.1 (s), Sample size = 405
Elapsed = 0.3 (s), Sample size = 608
Elapsed = 0.6 (s), Sample size = 912
Elapsed = 1.6 (s), Sample size = 1368
Elapsed = 3.8 (s), Sample size = 2052
Elapsed = 7.3 (s) > 5.0 (s), stopping the simulation.
Elapsed = 7.33 (s)
otv.View.ShowAll()
Total running time of the script: (0 minutes 17.804 seconds)