 OpenTURNS
Note
Go to the end to download the full example code.
Estimate failure probability sensitivity with simulation
In this example we estimate the sensitivity of a failure probability
with respect to the parameters of the input distribution using the
SimulationSensitivityAnalysis class.
For a failure event  with
input density
 , the sensitivity with respect
to
 is:

With Monte Carlo sampling this expectation is estimated by the empirical
mean over the input sample. With importance sampling with importance
density  , each realization is weighted by the likelihood ratio
 :

We first run a Monte Carlo reference, then importance sampling in the physical space, and finally importance sampling in the standard space mapped back to the physical space.
import openturns as ot
import openturns.viewer as otv

ot.RandomGenerator.SetSeed(0)
Define the model
A linear limit-state with Gaussian inputs.
distribution = ot.Normal([0.0] * 2, [1.0] * 2)
model = ot.SymbolicFunction(["x0", "x1"], ["x0 + 2.0 * x1"])
threshold = 3.0
Monte Carlo reference
With uniform weights the samples stored by the memoized model are enough.
memo_mc = ot.MemoizeFunction(model)
event_mc = ot.ThresholdEvent(
    ot.CompositeRandomVector(memo_mc, ot.RandomVector(distribution)),
    ot.Greater(),
    threshold,
)
algo_mc = ot.ProbabilitySimulationAlgorithm(event_mc)
algo_mc.setMaximumOuterSampling(100)
algo_mc.setBlockSize(500)
algo_mc.setMaximumCoefficientOfVariation(0.05)
algo_mc.run()
result_mc = algo_mc.getResult()
print("Monte Carlo Pf =", result_mc.getProbabilityEstimate())

sensitivity_mc = ot.SimulationSensitivityAnalysis(result_mc)
print("Monte Carlo sensitivity =", sensitivity_mc.computeEventProbabilitySensitivity())
print("Monte Carlo mean point =", sensitivity_mc.computeMeanPointInEventDomain())

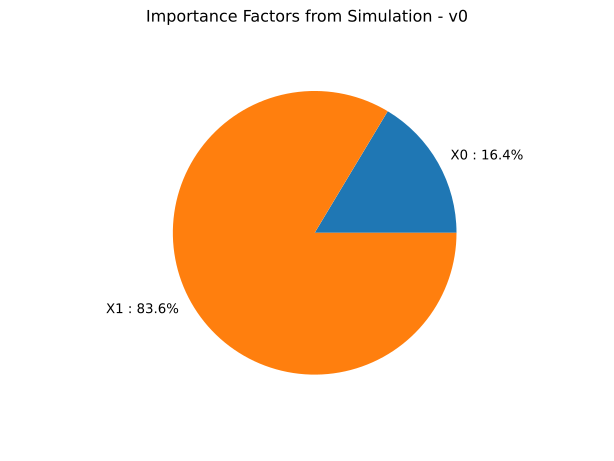
graph = sensitivity_mc.drawImportanceFactors()
view = otv.View(graph)
Monte Carlo Pf = 0.08888888888888888
Monte Carlo sensitivity = [mu_0 : 0.0646111, sigma_0 : 0.0303473, mu_1 : 0.145922, sigma_1 : 0.181368]
Monte Carlo mean point = [0.726875,1.64162]
Importance sampling in the physical space
The importance distribution is centered on the failure domain. The likelihood ratio must be passed as weights, otherwise the sensitivity is biased.
memo_is = ot.MemoizeFunction(model)
event_is = ot.ThresholdEvent(
    ot.CompositeRandomVector(memo_is, ot.RandomVector(distribution)),
    ot.Greater(),
    threshold,
)
importance = ot.Normal([1.0, 2.0], [1.0] * 2)
experiment = ot.ImportanceSamplingExperiment(importance)
algo_is = ot.ProbabilitySimulationAlgorithm(event_is, experiment)
algo_is.setMaximumOuterSampling(100)
algo_is.setBlockSize(500)
algo_is.setMaximumCoefficientOfVariation(0.05)
algo_is.run()
print("Importance sampling Pf =", algo_is.getResult().getProbabilityEstimate())

input_sample = memo_is.getInputHistory()
output_sample = memo_is.getOutputHistory()
weights = [
    distribution.computePDF(point) / importance.computePDF(point)
    for point in input_sample
]

sensitivity_is = ot.SimulationSensitivityAnalysis(
    event_is, input_sample, output_sample, weights
)
print(
    "Importance sampling sensitivity =",
    sensitivity_is.computeEventProbabilitySensitivity(),
)
print(
    "Importance sampling mean point =", sensitivity_is.computeMeanPointInEventDomain()
)
Importance sampling Pf = 0.09553770376063518
Importance sampling sensitivity = [mu_0 : 0.0789529, sigma_0 : 0.0414191, mu_1 : 0.150642, sigma_1 : 0.170741]
Importance sampling mean point = [0.826406,1.57678]
Importance sampling in the standard space
In practice importance sampling is often performed in the standard space
through a StandardEvent. The sensitivity with respect
to the physical distribution is then recovered by mapping the standard
input sample back to the physical space and weighting by the ratio of the
standard density over the importance density.
memo_phys = ot.MemoizeFunction(model)
phys_event = ot.ThresholdEvent(
    ot.CompositeRandomVector(memo_phys, ot.RandomVector(distribution)),
    ot.Greater(),
    threshold,
)
std_event = ot.StandardEvent(phys_event)
memo_std = ot.MemoizeFunction(std_event.getFunction())
std_event_is = ot.ThresholdEvent(
    ot.CompositeRandomVector(memo_std, std_event.getAntecedent()),
    std_event.getOperator(),
    std_event.getThreshold(),
)
std_importance = ot.Normal([1.0, 2.0], ot.CovarianceMatrix(2))
std_experiment = ot.ImportanceSamplingExperiment(std_importance)
std_algo = ot.ProbabilitySimulationAlgorithm(std_event_is, std_experiment)
std_algo.setMaximumOuterSampling(100)
std_algo.setBlockSize(500)
std_algo.setMaximumCoefficientOfVariation(0.05)
std_algo.run()
print("Standard-space Pf =", std_algo.getResult().getProbabilityEstimate())

std_input = memo_std.getInputHistory()
std_output = memo_std.getOutputHistory()
std_distribution = ot.Normal(2)
std_weights = [
    std_distribution.computePDF(point) / std_importance.computePDF(point)
    for point in std_input
]
phys_input = distribution.getInverseIsoProbabilisticTransformation()(std_input)

sensitivity_std = ot.SimulationSensitivityAnalysis(
    phys_event, phys_input, std_output, std_weights
)
print(
    "Standard-space sensitivity w.r.t. physical parameters =",
    sensitivity_std.computeEventProbabilitySensitivity(),
)
Standard-space Pf = 0.0870263073049596
Standard-space sensitivity w.r.t. physical parameters = [mu_0 : 0.0646741, sigma_0 : 0.0404083, mu_1 : 0.145542, sigma_1 : 0.186382]